Regulatory Reporting Pressure
150+ regulatory reports, frequent circular changes, manual mapping and constant inspection exposure.
Secure, compliant, enterprise-grade IT solutions for banks, NBFCs and cooperative banks worldwide — built to meet regional regulatory standards from day one. 12 years of banking and finance engineering, compliance-first delivery, and productised solutions trusted by financial institutions across markets.
Secure, compliant, enterprise-grade IT solutions for banks, NBFCs and cooperative banks worldwide — built to meet regional regulatory standards from day one. 12 years of banking and finance engineering, compliance-first delivery, and productised solutions trusted by financial institutions across markets.
Banking and financial services institutions are modernising under real pressure — integrating data across systems, meeting an expanding set of regulatory demands, and keeping systems secure, without disrupting live operations.
Three challenges recur: infrastructure that's costly and risky to modernise, data siloed across core banking, lending, CRM and other systems, and regulatory reporting still done manually — turning every cycle into a crunch where one error can trigger a compliance inquiry. The institutions that get ahead treat compliance, data and security as one connected problem.
150+ regulatory reports, frequent circular changes, manual mapping and constant inspection exposure.

Siloed CBS, lending, CRM and data that blocks trusted analytics, governance and AI-readiness.

Core systems and platforms that are costly to run and high-risk to upgrade without disrupting live operations.

High-volume back-office processes and paper-based branch operations that inflate cost and audit time.

Expanding cloud footprints and growing data volumes widen the attack surface, while uptime expectations leave no room for disruption.

Compliance, data and security, solved together — not as separate IT projects.
Each solution states the problem in your language, how Ahana actually delivers it, and the outcome.
THE PROBLEM
Banks often manually consolidate data from core banking and other systems to prepare RBI returns, creating reconciliation gaps, filing delays and errors. This falls short of RBI’s ADF expectation for automated, intervention-free reporting.
HOW AHANA HELPS
Ahana’s Data SBU builds a Centralised Data Platform (CDP) that serves as a single source of truth for regulatory data. It integrates directly with core banking and other source systems, applies RBI validation and reconciliation rules, and generates submission-ready returns for the CIMS portal, with end-to-end data lineage and audit trails. Powered by Ahana’s productised Regulatory Reporting Solution, the CDP includes 50+ pre-built RBI returns, with templates updated in line with RBI circulars. It supports ADF compliance while leveraging the bank’s existing infrastructure and licences.
Audit-ready reports, drastically reduced quarter-end effort, defensible data lineage.

THE PROBLEM
Provisioning and restructuring calculations across the loan book are manual, error-prone, and difficult to defend in an regualtory inspection.
HOW AHANA HELPS
The Data SBU builds an automated provisioning and restructuring engine on your core banking data, applying current regulatory requirements and supervisory guidelines — including edge cases like MSME and COVID-restructured accounts — so classifications update as the rules change, with a full audit trail.
Inspection-ready provisioning with near-zero manual reconciliation.
THE PROBLEM
Credit teams rely on lagging indicators, so default risk surfaces too late, and decisioning is slower than digital-first competitors.
HOW AHANA HELPS
Ahana.AI builds production-grade default-prediction models using lending and bureau data — not experimental demos — with explainability for credit and risk committees and responsible-AI governance built in. The Data SBU prepares the underlying platform.
Earlier risk signals and faster, more consistent credit decisions.
THE PROBLEM
Back-office teams rely on manual, time-consuming processes for transaction reconciliation and exception handling. This slows failed-transaction reversals, risking RBI turnaround-time breaches, customer compensation and audit exposure.
HOW AHANA HELPS
Ahana combines its productised reconciliation engine with intelligent automation to streamline banking operations. ReconSphere, Ahana’s reconciliation platform, automates multi-source matching with Maker-Checker controls and a complete audit trail. It is proven across M-Pesa and Visa card settlement workflows. Complementing this, Ahana’s Intelligent Automation SBU, a UiPath partner, automates account maintenance, exception routing, posting and reporting. Using its RapidAutomate and Quick Strike accelerators, common banking workflows are deployed through pre-built components, reducing the need for development from scratch.
Faster settlement and reversals within TAT, fewer manual touchpoints, and audit-ready exception handling.
THE PROBLEM
Paper-based branch registers slow audits, inflate stationery and logistics cost, and create compliance gaps across the network.
HOW AHANA HELPS
Ahana digitises branch registers end-to-end (Data + Application Development), giving a searchable, audit-ready digital record across every branch — designed for regulatory inspection readiness from the start.
100% elimination of manual registers, 60% savings in stationery and logistics, 70% faster audits.
THE PROBLEM
Screening and looking up customers or accounts across large datasets is slow at scale.
HOW AHANA HELPS
The Data SBU builds high-performance bulk search across large banking datasets, supporting compliance screening (AML/KYC), customer and account discovery, and audit queries at volume.
Rapid search across millions of records and faster compliance screening.
THE PROBLEM
Branch and relationship sales teams lack consistent preparation and next-best-action prompts, so cross-sell and conversion vary widely.
HOW AHANA HELPS
Application Development and Ahana.AI build a digital sales assistant that equips relationship managers with customer context, call preparation and cross-sell prompts — making engagement consistent instead of person-dependent.
More consistent sales preparation and steadier conversion.
Banking isn't a vertical Ahana entered recently — it's the core of the business. 12 years of engineering for financial institutions means the people building the solutions for your system have supported clients through regulatory audits and modernised live cores without data loss.
Years in BFSI
BFSI Specialists
BFSI Clients
Regulatory Reports Covered
Karnataka Bank — Modernizing PostgreSQL performance with faster restarts, optimized storage, and improved query efficiency through Ahana’s hands-on database expertise.
Kotak Securities — 33% lower database footprint, ~₹3.1 lakh saved monthly, zero trading disruption: how Ahana optimized Kotak Securities' AWS DocumentDB
India's largest Small Finance Bank — a multi-SBU digital transformation engagement.
Productised RBI Reporting Solution — purpose-built compliance automation for cooperative banks, RRBs and NBFCs, with audit-ready outputs across 50+ RBI reports (CRILC, AFI, Return A, ADF, off-site monitoring, ATM/IMPS/MPS).
The highest-conviction trust step in a BFSI decision. One deep case; more available on request.
CASE STUDY · BANKING
Challenge
Following a core banking migration, retrieving historical data and consolidating information for RBI reporting became challenging. Production-level data extraction, inconsistencies across reports and extensive cross-team coordination stretched reporting cycles to 10–15 days.
Approach
Ahana implemented a Central Data Platform to centralise and govern data, enable self-service reporting, and automate report generation while reducing manual dependencies.
Outcome
The bank generated its RBI Form 121 report within 2–3 hours. Today, 23+ regulatory and ADF reports are auto-generated, MIS is generated daily, and manual effort is reduced for 30–40 staff. Reporting that once took 10–15 days can now be completed in minutes.

A 2-week pilot on one quarterly RBI return cycle, or a discovery workshop, before scaling.

ISO 27001:2022 + ISO 9001:2015, a BFSI-specific framework, SOC2 Type 2 certified

Across data, cloud, automation, application and other services.

Delivered 20+ technologies for 100+ clients.

Member since 2016; Karnataka Regional Council since 2025.
Practical guides, regulatory updates and case-backed thinking for IT and compliance leaders in banking and finance. No fluff, no vendor-speak.
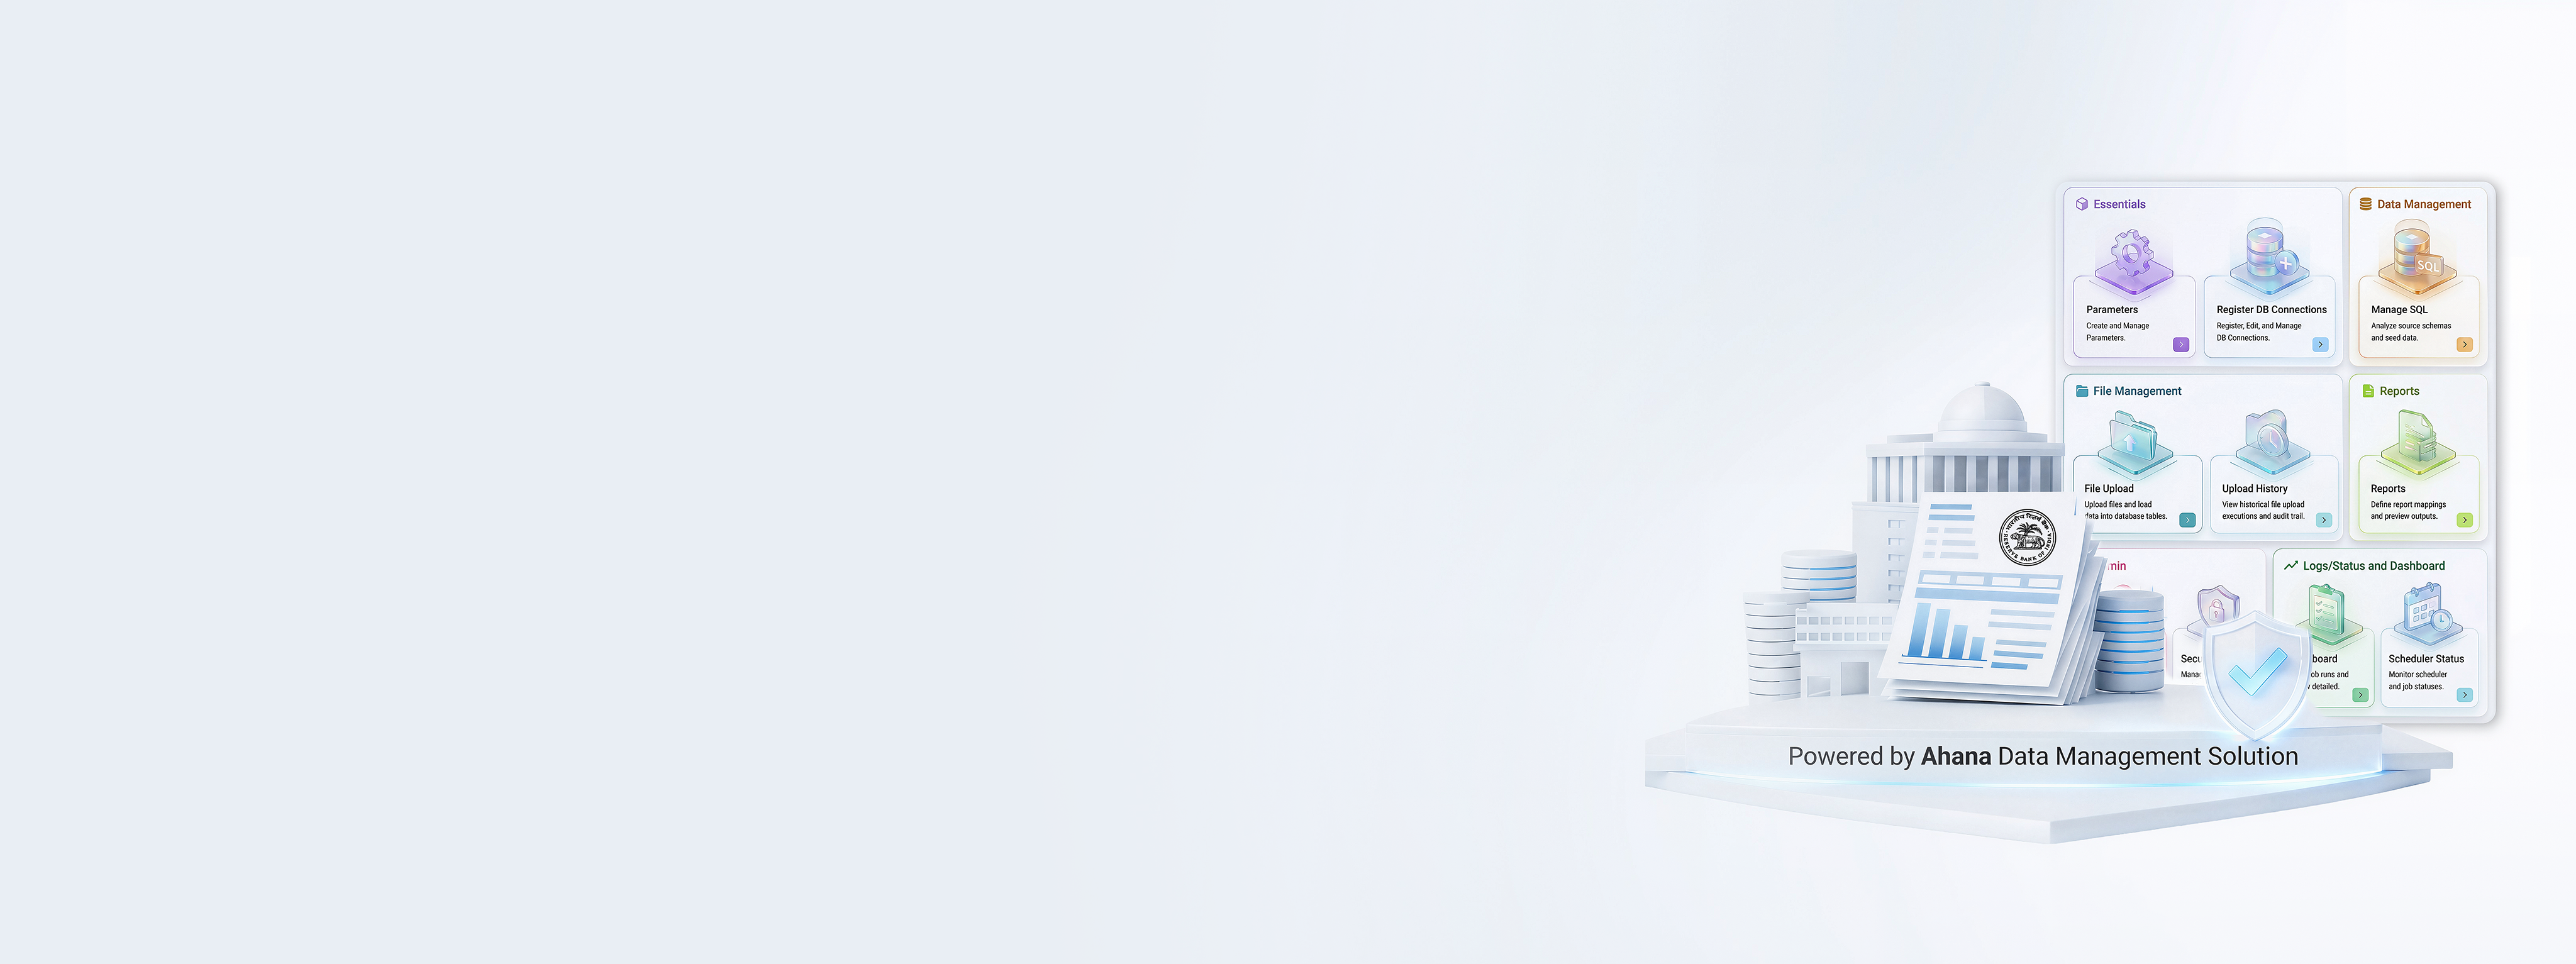
What’s changed and what banks need to do now
From CRILC to ADF and off-site monitoring, the scope of RBI obligations keeps expanding. We walk through the latest circular changes, common mapping failures, and how productised automation changes the economics of compliance.
Read More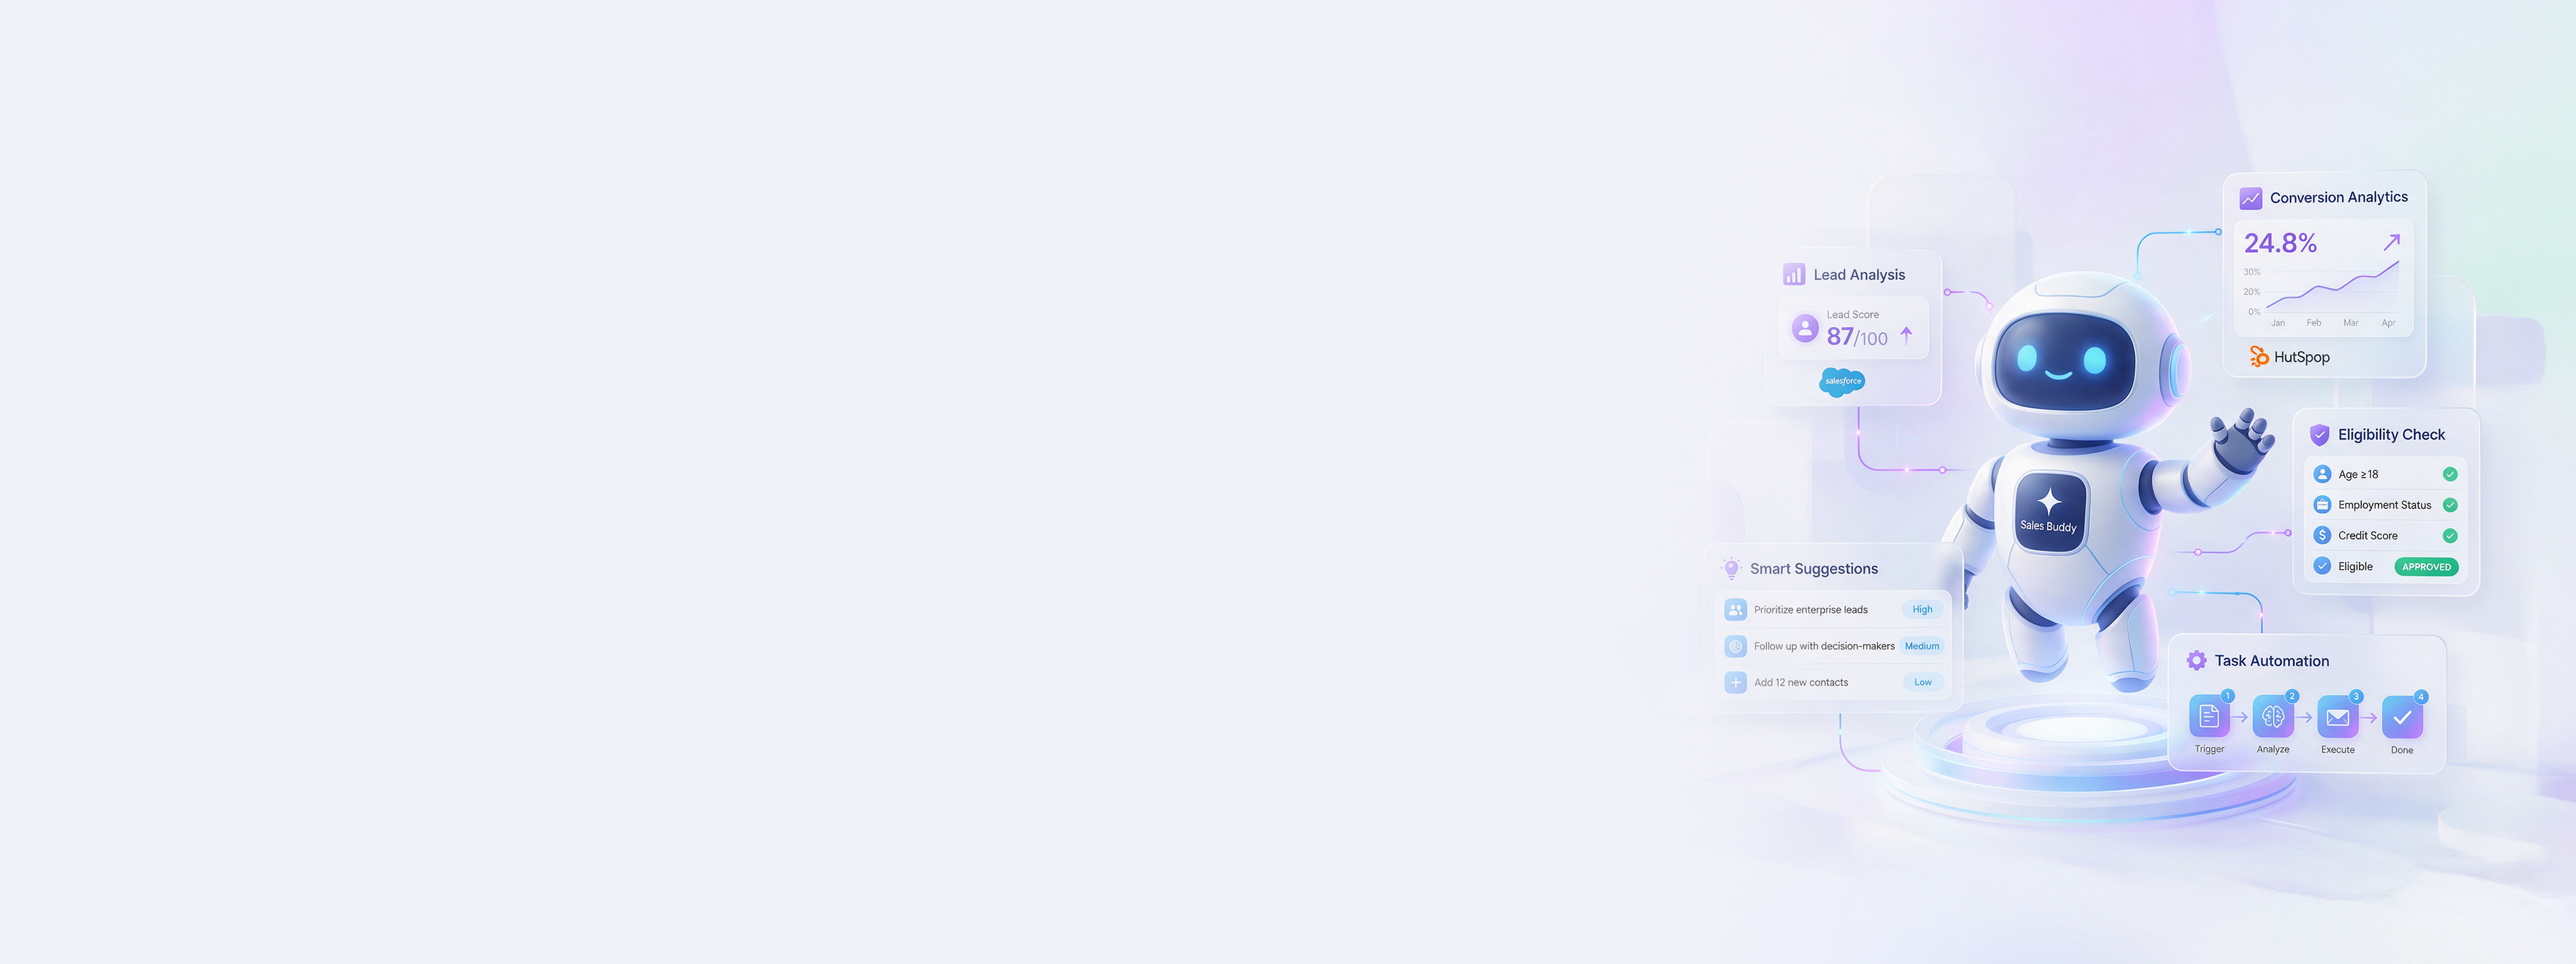
Support Before, During and After Every Customer Call
Empower your sales teams with AI-driven insights, personalized engagement, and intelligent automation—boosting conversions by 35%, improving productivity by 40%, and automating eligibility assessments with 95% accuracy.
Read More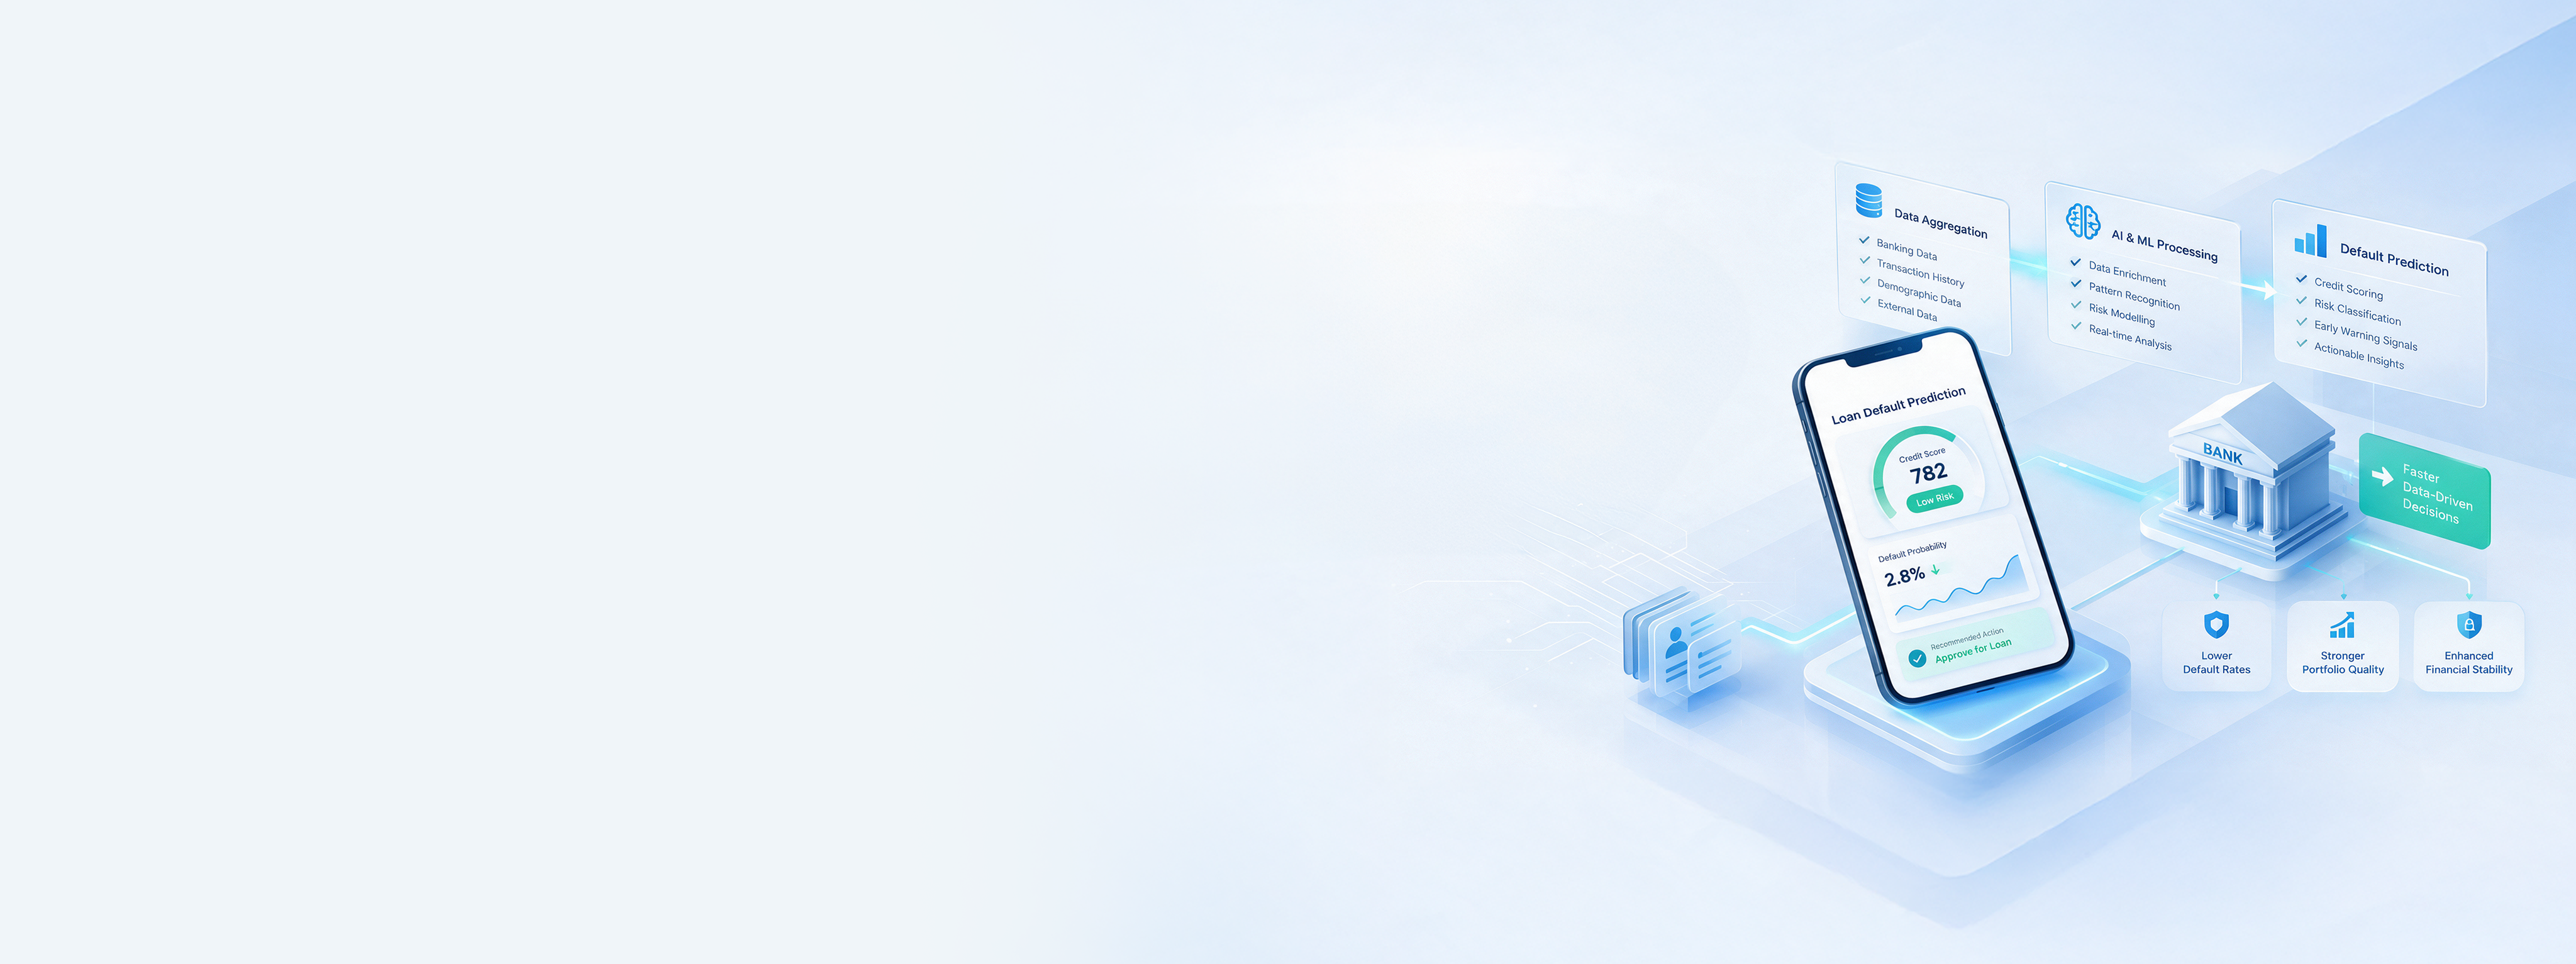
Credit Risk AI That Banks Can Defend
Production-grade fault prediction isn’t a demo. Here’s what explainability for credit committees actually requires, and how responsible-AI governance is built in from day one.
Read More
What Replacing 15+ Paper Registers Taught Us About Risk
A leading private bank, paper registers, and a head office with no visibility into branch activity. These are the decisions that made the digitisation work, and what we'd do the same way again.
Read MoreAhana's BFSI delivery runs on a curated, audited stack — chosen for security, regulatory defensibility, and proven performance in Indian financial institutions. No experimental tooling in live regulatory pipelines.